SELLERSTACK HMRC GUIDE · UPDATED FOR 2026
HMRC Side Hustle Tax UK 2026
Understand marketplace reporting, trading income, the £1,000 Trading Allowance, Self Assessment and Making Tax Digital — without confusing sales, platform reports, taxable profit and tax actually due.
If you sell through eBay, Vinted, Amazon, Etsy, Depop, TikTok Shop or another online platform, you may have seen warnings about a new UK “side hustle tax”.
That phrase causes more confusion than it solves.
There is no separate tax called the side hustle tax.
What has changed is the amount of seller information certain digital platforms collect and report to HMRC.
Platform reporting does not automatically mean that a seller owes Income Tax, has become self-employed or needs to pay tax on every pound shown in their marketplace account.
The underlying activity still matters.
Someone selling old clothes and household possessions can be in a very different tax position from somebody regularly buying products specifically to resell for profit.
This guide separates the rules that online sellers most often mix together: platform reporting, trading status, gross trading income, the £1,000 Trading Allowance, taxable profit, Self Assessment and Making Tax Digital.
Do Online Sellers Have to Pay a New Side Hustle Tax?
No new tax has been created simply because you sell through an online marketplace.
If you are clearing unwanted personal possessions, those sales do not automatically become taxable trading income because a platform reports information to HMRC.
If you buy or make goods intending to sell them for profit, HMRC says you are probably trading.
Traders then need to look at their gross trading income, the £1,000 Trading Allowance, allowable expenses and whether Self Assessment is required.
The useful order is:
Reporting → Trading → Allowance → Profit → Action.
Important Tax Information
This guide provides general information for UK online sellers. It is not personalised tax, accounting or legal advice.
Tax treatment depends on your circumstances, including the nature of your activity, other income, expenses and where relevant your wider tax position.
Check current HMRC guidance or speak to a qualified tax professional if you are unsure about your obligations.
Check the Seller Thresholds Before You Guess
Use the SellerStack HMRC Sales & Tax Threshold Checker to compare your figures with important UK trading, platform-reporting, VAT and Making Tax Digital thresholds.
1. There Is No New UK “Side Hustle Tax”
The digital platform reporting rules are often described online as though HMRC introduced a new tax on people selling second-hand goods.
That is misleading.
Since 1 January 2024, certain digital platforms have had additional obligations to collect, check and report seller information.
Those rules give HMRC more information.
They do not replace the existing rules that determine whether somebody is trading, has taxable income or has made a chargeable capital gain.
Keep the Two Questions Separate
                Platform reports information
                ≠
                seller automatically owes tax
Reporting Is a Data-Sharing Rule
The purpose of platform reporting is to provide HMRC with information about qualifying platform activity.
Whether that activity creates tax is a separate question.
2. Five Numbers Online Sellers Must Keep Separate
Most confusion comes from treating several completely different numbers as though they measure the same thing.
1. Platform Reporting Figures
Information a digital platform may be required to provide to HMRC under the platform reporting rules.
2. Gross Trading Income
Your relevant trading receipts before deducting business expenses.
3. £1,000 Trading Allowance
A tax allowance that can apply to qualifying gross trading income.
4. Taxable Trading Profit
The amount remaining after the appropriate tax calculation, using allowable expenses or the Trading Allowance where applicable.
5. Tax Actually Due
The final tax position after taking account of your taxable income, relevant allowances and wider circumstances.
£1,000 of Sales Does Not Mean £1,000 of Taxable Profit
The Trading Allowance relates to gross trading income.
Profit is a different figure, and tax actually due is another calculation again.
3. How Digital Platforms Report Seller Information to HMRC
UK digital platform reporting rules require qualifying platform operators to collect seller information and report certain activity to HMRC.
For people selling goods, HMRC currently provides a reporting exclusion where both of these conditions are met:
Fewer Than 30 Sales
The seller makes fewer than 30 relevant sales of goods during the calendar year.
€2,000 or Less
The total consideration is no more than €2,000, approximately £1,700 depending on exchange rates.
Both conditions must be satisfied for this particular goods-seller reporting exclusion.
In practical terms, reaching 30 sales or exceeding the €2,000 amount can mean the seller no longer falls within that exclusion.
This Is Not a Tax-Free Threshold
The 30-sale / €2,000 rules concern platform reporting.
They do not determine whether somebody is trading, whether the £1,000 Trading Allowance applies or whether tax is due.
Platform Reporting Uses a Calendar Year
Platform reporting information is collected using a 1 January to 31 December reporting period.
Platforms then report the relevant information by the following January.
UK Tax Uses a Different Period
The UK tax year normally runs:
                6 April
                →
                5 April
This means a platform’s annual report cannot simply be copied into a tax calculation without considering the different periods and your own underlying records.
Platforms Must Also Give Sellers Their Reported Information
HMRC says platform operators must provide sellers with a copy of information reported to HMRC.
Keep it with your records, but do not treat it as a substitute for your own bookkeeping.
4. Are You Actually Trading?
The nature of the activity matters more than the marketplace name.
HMRC says you are probably trading if you sell goods that you:
- bought intending to sell for a profit
- made with the intention of selling
For resellers, this can include stock sourced through:
- charity shops
- car boot sales
- retail clearance
- wholesalers
- online marketplaces
- auctions
- liquidation or job lots
Personal Disposal
You previously bought or received the item for your own use and later decided that you no longer wanted it.
This does not automatically amount to trading.
Commercial Resale
You acquired or made the product because you expected to sell it to somebody else.
HMRC says this is likely to be trading activity.
The Same Pair of Trainers Can Have a Different Tax Context
You sell a pair of trainers you bought two years ago, wore personally and no longer want.
That is very different from buying a pair of discounted trainers this morning specifically because you expect to resell them for more money.
The marketplace may be identical.
The underlying activity is not.
Selling Commercially on eBay?
eBay’s private-versus-business account rules are separate from HMRC’s tax thresholds. Our guide explains why goods bought or made for resale should not be treated as private selling simply because revenue is still small.
5. What if You Are Only Selling Personal Possessions?
Selling unwanted possessions is not automatically a trade.
HMRC says people are unlikely to pay tax simply because they sell personal items from their home, such as belongings from a loft, wardrobe or garage.
That does not mean every disposal of a personal possession can be ignored for every type of tax.
Valuable Personal Possessions Can Raise a Separate Capital Gains Question
HMRC says Capital Gains Tax may need to be considered if you make a gain when disposing of certain personal possessions for £6,000 or more.
Examples can include jewellery, paintings, antiques, coins, stamps and some sets of possessions.
A £6,000 selling price does not automatically mean Capital Gains Tax is due. The relevant gain and the applicable CGT rules still need to be considered.
Two Different Questions
                Selling personal possessions
                →
                usually not trading
                Valuable possession sold at a gain
                →
                check separate Capital Gains Tax rules
Mainly Clearing Clothes and Personal Possessions on Vinted?
Read our Vinted HMRC Tax Rules guide for the more focused distinction between wardrobe clear-outs, platform reporting and buying products specifically to resell.
6. How Does the £1,000 Trading Allowance Work?
The Trading Allowance provides up to £1,000 of relief against qualifying gross trading income in a tax year.
The key word is: gross.
Gross trading income means the relevant trading receipts before deducting expenses.
If Gross Trading Income Is £1,000 or Less
Where qualifying annual gross trading income is £1,000 or less, full relief can mean you do not need to tell HMRC about that trading income, although exceptions exist.
You should still keep appropriate records.
If Gross Trading Income Is More Than £1,000
HMRC says you need to tell them about relevant gross trading income above £1,000.
Where eligible, you may then be able to choose between:
Actual Allowable Expenses
Deduct qualifying business expenses when calculating trading profit.
Trading Allowance
Elect to deduct up to £1,000 instead of deducting those actual expenses, where the rules allow.
You Do Not Normally Claim Both Against the Same Trading Income
If you use the Trading Allowance to calculate the relevant profit, you cannot also deduct the actual expenses associated with that same income.
This matters to resellers because stock, postage, marketplace fees and other costs can easily exceed £1,000.
£6,000 Gross Trading Income
Imagine a reseller has:
- gross trading income: £6,000
- qualifying actual expenses: £3,000
Using actual allowable expenses would produce a simplified trading profit of:
£6,000 − £3,000 = £3,000
Using the £1,000 Trading Allowance instead would produce:
£6,000 − £1,000 = £5,000
In that simplified example, actual allowable expenses produce the lower figure.
Your circumstances determine which method is available and appropriate.
7. What Business Expenses Can a Reseller Potentially Claim?
If you are trading and calculate profit using actual allowable business expenses, the costs should relate to the business.
HMRC specifically identifies the cost of goods bought for resale as an allowable expense for qualifying self-employed businesses.
Stock for Resale
Goods bought specifically to sell as part of the business.
Marketplace Costs
Relevant selling fees and other qualifying business charges should be recorded separately from the sale itself.
Postage & Delivery
Qualifying business delivery and fulfilment expenses can form part of the cost of trading.
Packaging
Business-use mailers, boxes, tape, labels and packing materials should be recorded where relevant.
Business Software & Services
Certain qualifying software, subscriptions and services used for the business may also be relevant.
Other Business Costs
Other expenses may be allowable depending on what the cost is and whether it satisfies HMRC’s rules.
Personal Spending Is Not a Business Expense
HMRC does not allow the cost of goods or materials bought for private use to be claimed as stock-for-resale expenses.
Where an expense has both business and personal use, separate rules may apply.
Keep Sales, Payouts, Expenses and Profit Separate
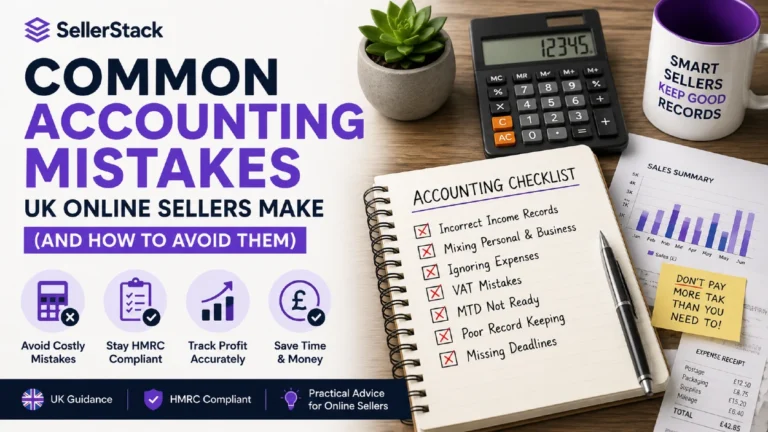
Our Accounting Mistakes guide explains why marketplace payouts are not the same as sales, how missing costs can distort profit and why clean records matter as a reselling business grows.
8. Sales Income Is Not the Same as Taxable Profit
A reseller can generate substantial sales without making the same amount in profit.
Suppose a business receives £20,000 of trading income during the year.
That does not mean £20,000 is the profit on which tax will necessarily be calculated.
Simplified Trading Profit Principle
                trading income
                -
                allowable business expenses
                =
                trading profit
Where the Trading Allowance is used instead of actual expenses, that calculation changes accordingly.
The amount of Income Tax ultimately due then depends on the seller’s wider tax position.
Crossing £1,000 Does Not Mean Every Pound Is Suddenly Taxed
The £1,000 figure is not a cliff where £1,001 of receipts suddenly becomes £1,001 of taxable profit.
Crossing the threshold changes the reporting and calculation questions you need to consider.
9. When Does an Online Seller Need Self Assessment?
If you have gross trading income above £1,000, HMRC says you need to tell them about the income.
For many sole-trader sellers, this means registering for Self Assessment where they are not already registered.
There can also be other reasons somebody needs to complete a Self Assessment return.
Ask These Questions in Order
1. Am I actually trading?
If not, the Trading Allowance may not be the relevant starting point.
2. What is my gross trading income?
Calculate it before expenses across your relevant trading activity.
3. Is it above £1,000?
If so, check your requirement to notify HMRC and complete
Self Assessment.
4. How will I calculate profit?
Consider actual allowable expenses versus the Trading Allowance
where eligible.
10. Self Assessment Deadlines for the 2025/26 Tax Year
The 2025/26 UK tax year ended on 5 April 2026.
The main Self Assessment dates are:
| Date | What it means |
|---|---|
| 5 October 2026 | Normal deadline to tell HMRC if you newly need to complete Self Assessment for 2025/26 |
| 31 October 2026 | Normal deadline for paper tax returns |
| 30 December 2026 | Deadline to file online if eligible and asking HMRC to collect certain tax through a PAYE tax code |
| 31 January 2027 | Normal online filing deadline and deadline to pay Self Assessment tax due |
| 31 July 2027 | Second payment on account where one is required |
As of October 2026, the 5 October Registration Date Has Passed
If you needed to register for 2025/26 but did not do so by 5 October 2026, do not simply wait until January.
HMRC says people registering after 5 October may be given a different filing deadline — normally three months from the date of HMRC’s letter or email.
However, tax owed for 2025/26 must still normally be paid by 31 January 2027.
Late notification can also create penalty consequences, particularly where tax remains unpaid.
11. Making Tax Digital for Income Tax Is Now Live
Making Tax Digital for Income Tax began its mandatory rollout on 6 April 2026.
It does not currently apply to every marketplace seller or every sole trader.
The rollout is based on qualifying income.
HMRC defines qualifying income for this purpose as total gross income from self-employment and property before expenses and tax, based on the relevant previous tax return.
| Tax return used | Qualifying income | MTD start date |
|---|---|---|
| 2024/25 | More than £50,000 | 6 April 2026 |
| 2025/26 | More than £30,000 | 6 April 2027 |
| 2026/27 | More than £20,000 | 6 April 2028 |
What Changes Under MTD?
If Making Tax Digital for Income Tax applies to you, the system requires digital record keeping and compatible software.
- keep required business records digitally
- use MTD-compatible software
- send quarterly updates to HMRC
- complete the required end-of-year tax process
- continue paying tax by the normal relevant deadline
MTD Uses Gross Qualifying Income — Not Final Profit
A reseller can have relatively modest profit after stock costs, marketplace fees and postage while still having qualifying income high enough to enter MTD.
Do not wait until your profit reaches £50,000 before checking whether the 2026 requirement applies.
Monitor Trading, Reporting and MTD Thresholds Separately
Use the SellerStack HMRC Sales & Tax Threshold Checker as a planning tool, then verify important decisions against current HMRC guidance.
12. What Records Should Online Sellers Keep?
Good records are useful long before the business reaches a tax or MTD threshold.
HMRC says self-employed businesses should keep records of sales, income and business expenses, along with evidence supporting those figures.
- marketplace sales records
- platform statements
- stock purchase receipts and invoices
- postage and courier costs
- packaging expenses
- marketplace fees
- advertising costs
- bank statements
- refund and return records
- other relevant business receipts and invoices
How Long Should Self-Employed Records Be Kept?
HMRC says relevant Self Assessment business records normally need to be kept for at least five years after the 31 January submission deadline for the relevant tax year.
Start Keeping Records Before You Need Them
Reconstructing months of charity-shop receipts, postage costs, marketplace deductions and stock purchases after crossing a threshold is much harder than recording them as you go.
13. Marketplace Payouts Are Not the Same as Sales or Profit
One of the most common seller bookkeeping mistakes is recording only the amount that reaches the bank account.
A marketplace may deduct charges before sending the payout.
£100 Customer Sale — £85 Bank Payout
Imagine a marketplace transaction shows:
- customer sale: £100
- marketplace deductions: £15
- payout to bank: £85
The £85 deposit tells you how much cash the platform transferred.
It does not by itself provide a complete record of the sale, marketplace cost and business profit.
Keep the Numbers Separate
                sales income
                ≠
                marketplace payout
                ≠
                business profit
Avoid the Accounting Mistakes That Distort Seller Numbers
Read our guide to common accounting mistakes for UK online sellers, including payouts, Trading Allowance confusion, missed expenses, stock value and cashflow.
14. What if You Sell on Several Marketplaces?
Using separate apps does not necessarily create separate tax allowances for each marketplace.
If you are trading across eBay, Vinted, Etsy, Amazon or other channels, the relevant trading income needs to be considered together where the tax rules require.
£600 on eBay + £500 on Vinted
Imagine both sets of sales form part of the same person’s qualifying trading activity.
Looking at each marketplace separately could make both appear to be below £1,000.
But the combined gross trading income is:
£1,100.
The £1,000 Trading Allowance is not a separate £1,000 allowance for every app used.
Platform Reporting Can Still Be Platform-Specific
Each platform operator has its own reporting obligations for the activity it facilitates.
Your tax calculation, however, needs to consider your relevant income under HMRC’s rules rather than treating each marketplace account as an isolated business universe.
15. What if You Have a Job and a Reselling Side Hustle?
Having PAYE employment does not prevent you from also having self-employment or trading income.
But the Trading Allowance should not be confused with the Personal Allowance used within the wider Income Tax system.
Two Different Allowances
                £1,000 Trading Allowance
                ≠
                Personal Allowance
Where a taxable trading profit exists, it forms part of your wider tax position.
The actual amount of tax due depends on your total circumstances, including other taxable income and the tax rules that apply to you.
Self-employed profits can also have National Insurance implications depending on the level of profit and the rules for the relevant tax year.
A Job Does Not Give the Side Hustle a Separate Tax-Free Income Band
Do not assume that because PAYE tax is already taken from your salary, marketplace trading income can be ignored.
Check the trading and Self Assessment rules separately.
16. The SellerStack HMRC Decision Framework
When marketplace tax headlines become confusing, work through the questions in this order.
Reporting → Trading → Allowance → Profit → Action
-
Reporting
Has a platform reported or potentially reported your seller information? Treat this as a data-sharing question first. -
Trading
Are you mainly disposing of personal possessions, or are you buying or making products specifically to sell? -
Allowance
If you are trading, calculate gross trading income and consider the £1,000 Trading Allowance rules. -
Profit
Work out the relevant trading profit using the appropriate allowable-expense or Trading Allowance method. -
Action
Check whether you need Self Assessment, MTD, further records or professional advice.
| Situation | What to check next |
|---|---|
| Clearing normal unwanted possessions | Usually not trading; consider separate CGT rules for valuable possessions where relevant |
| Buying products specifically to resell | Trading rules and gross trading income |
| Making products specifically to sell | Trading rules and gross trading income |
| Gross trading income £1,000 or less | Check Trading Allowance eligibility and any exceptions |
| Gross trading income above £1,000 | Check requirement to tell HMRC and Self Assessment |
| Platform reports 30+ sales or higher value | Do not assume tax is due; assess the underlying activity |
| Qualifying MTD income above relevant threshold | Check current MTD requirements and compatible software |
| You have PAYE employment as well | Consider side-hustle profit within your wider tax position |
Continue Through the SellerStack Business-Numbers Path
Explore HMRC guidance, platform reporting, bookkeeping, seller records, VAT and business thresholds without treating every rule as the same number.
17. Common HMRC and Side Hustle Tax Mistakes
Nine Rules Online Sellers Commonly Mix Up
-
Thinking platform reporting means tax is automatically due.
Reporting and tax liability are separate questions. -
Treating the €2,000 / 30-sale reporting rule as a tax allowance.
It is a platform reporting rule, not the £1,000 Trading Allowance. -
Thinking £1,000 means profit.
The Trading Allowance is based on qualifying gross trading income. -
Looking at each marketplace separately.
Relevant trading income may need to be considered together. -
Recording the bank payout as the sale.
Marketplace deductions can make the payout lower than the underlying transaction value. -
Claiming the Trading Allowance and actual expenses together.
You do not normally deduct both against the same relevant income. -
Assuming every personal possession sale is completely irrelevant.
Valuable possessions can raise separate Capital Gains Tax questions. -
Thinking MTD is based on taxable profit.
MTD qualifying income is based on relevant gross self-employment and property income. -
Waiting until January to reconstruct the whole year.
Maintain sales, stock and expense records as you trade.
18. SellerStack Online Seller Tax Checklist
- Separate personal possessions from stock acquired for resale.
- Keep platform reporting rules separate from tax rules.
- Track gross trading income before expenses.
- Combine relevant trading activity where HMRC rules require it.
- Do not treat marketplace payouts as your complete sales records.
- Keep stock purchase receipts and invoices.
- Keep marketplace statements and fee records.
- Keep postage and packaging records.
- Check whether the £1,000 Trading Allowance applies.
- Compare the Trading Allowance with actual allowable expenses where appropriate.
- Check whether you need to register for Self Assessment.
- If registration was due by 5 October 2026 and was missed, act now rather than waiting.
- Note the 31 October 2026 paper filing deadline.
- Note the 31 January 2027 online filing and payment deadline.
- Check whether MTD for Income Tax applies to you.
- Use digital records if you are within MTD requirements.
- Retain relevant business records for the required period.
- Check separate CGT rules where valuable personal possessions are sold.
- Consider professional advice where your circumstances are unclear or more complex.
Which Situation Sounds Most Like You?
I am only clearing unwanted clothes and household possessions:
You are not automatically trading merely because sales are made
through a marketplace. Check separate CGT rules if valuable
possessions are involved.
I buy products specifically to flip:
HMRC says you are probably trading. Start tracking gross trading
income and business expenses properly.
My gross trading income is £1,000 or less:
Check whether full Trading Allowance relief applies and whether
any exception means HMRC still needs to be told.
My gross trading income is above £1,000:
Check Self Assessment requirements and decide how taxable profit
should be calculated.
A marketplace has reported my details:
Do not assume this is a tax bill. Assess whether the activity
was trading and use your own records to calculate the tax-year
figures.
I have a job as well as reselling income:
The Trading Allowance is not another Personal Allowance.
Consider any taxable business profit within your wider position.
My self-employment/property income is becoming substantial:
Check Making Tax Digital using qualifying gross income rather
than waiting for taxable profit to reach the MTD threshold.
Frequently Asked Questions
Is there a new side hustle tax in the UK?
No separate tax called the “side hustle tax” has been introduced. Digital platforms have new reporting obligations, but existing tax rules still determine whether the underlying activity is taxable.
Does HMRC tax everyone who sells on eBay or Vinted?
No. Selling through a marketplace does not automatically create taxable trading income. HMRC distinguishes activities such as disposing of personal possessions from buying or making goods specifically to sell for profit.
Does selling more than £1,000 mean I owe tax?
Not automatically. The £1,000 Trading Allowance relates to qualifying gross trading income. If you are not trading, the figure may not be the relevant test. If you are trading and gross income exceeds £1,000, you need to consider HMRC reporting, profit calculation and your wider tax position.
Is the £1,000 Trading Allowance based on profit?
No. It relates to gross qualifying trading income before business expenses.
Can I deduct expenses as well as the £1,000 Trading Allowance?
You do not normally use the Trading Allowance and also deduct the actual expenses associated with the same relevant trading income. Where eligible, you compare the available methods.
Can stock bought for resale be an allowable expense?
HMRC specifically lists goods for resale as an allowable business expense for qualifying self-employed businesses. Personal purchases are not deductible as resale stock.
What is the 30-sales rule?
It forms part of the digital platform reporting rules for sales of goods. The reporting exclusion applies where both fewer than 30 sales are made and consideration does not exceed €2,000 in the calendar year. It is not a tax-free allowance.
If eBay reports me to HMRC, do I owe tax?
Not simply because a report has been made. HMRC states that platform reporting does not automatically mean tax is owed. The underlying activity and applicable tax rules still matter.
If I sell 35 old items from my wardrobe, am I trading?
Not automatically. The number of marketplace transactions can affect platform reporting, but selling personal possessions is different from buying or making products specifically to sell.
Do personal possessions ever create tax?
They can in some circumstances. HMRC says Capital Gains Tax may need to be considered where a gain is made on certain personal possessions disposed of for £6,000 or more.
Do I need to combine eBay and Vinted sales?
If the sales form part of your relevant trading activity, you should consider the trading income under HMRC’s rules rather than assuming each marketplace receives a separate £1,000 allowance.
Does marketplace reporting use the UK tax year?
No. Digital platform reporting generally uses a calendar-year reporting period, while the UK tax year runs from 6 April to 5 April.
When was the deadline to register for 2025/26 Self Assessment?
The normal deadline for someone newly needing Self Assessment for 2025/26 was 5 October 2026.
What if I missed the 5 October 2026 registration deadline?
Register as soon as possible. HMRC says people registering after 5 October may receive a different filing deadline, normally three months from the date of HMRC’s letter or email, but tax due still normally needs to be paid by 31 January 2027.
When is the 2025/26 online tax return due?
The normal online Self Assessment filing deadline is 31 January 2027, which is also the normal deadline to pay the Self Assessment tax due.
Is Making Tax Digital now compulsory?
It became compulsory from 6 April 2026 for qualifying sole traders and landlords whose 2024/25 qualifying income exceeded £50,000. The threshold expands to over £30,000 from April 2027 and over £20,000 from April 2028.
Is the MTD threshold based on profit?
No. HMRC describes qualifying income as gross income from self-employment and property before expenses and tax.
How long should a self-employed seller keep records?
HMRC says Self Assessment business records normally need to be retained for at least five years after the 31 January submission deadline for the relevant tax year.
I already pay tax through my job. Do I still need to report reselling income?
Potentially. PAYE employment and self-employed trading income are separate sources. If your marketplace activity amounts to trading, check the Trading Allowance and Self Assessment rules even if you already pay tax through employment.
Marketplace Reporting Is Not the Same Thing as a Tax Bill
The phrase “side hustle tax” makes several separate rules sound like one new charge.
They are not one rule.
A platform can report seller information without that person automatically owing tax.
Somebody can be trading before a platform reporting threshold is reached.
The £1,000 Trading Allowance relates to gross trading income, not marketplace sales generally and not profit.
And the amount deposited into your bank account is not automatically your sales income or taxable profit.
Keep the questions in the right order:
Reporting → Trading → Allowance → Profit → Action.
Once those numbers are separated, the HMRC position becomes much easier to understand and much easier to record properly.
Check the HMRC Thresholds Against Your Own Seller Figures
Enter your trading and seller figures into the SellerStack HMRC Sales & Tax Threshold Checker to identify which reporting, tax, VAT and Making Tax Digital thresholds may need closer attention.
Open HMRC Threshold Checker →Official HMRC Sources and Important Information
The reporting, allowance, Self Assessment and Making Tax Digital information in this guide was reviewed against current HMRC and GOV.UK guidance, including:
- GOV.UK — Selling Goods or Services on a Digital Platform
- GOV.UK — Check if You Need to Tell HMRC About Income From Online Platforms
- GOV.UK — Tax-Free Allowances on Property and Trading Income
- GOV.UK — Expenses if You’re Self-Employed: Reselling Goods
- GOV.UK — Self Assessment Tax Return Deadlines
- GOV.UK — Making Tax Digital for Income Tax
- GOV.UK — Business Records if You’re Self-Employed
- GOV.UK — Capital Gains Tax on Personal Possessions
Tax Accuracy & Important Information
Last reviewed: October 2026.
HMRC tax rules, thresholds, Self Assessment procedures, Making Tax Digital requirements and digital platform reporting rules can change.
SellerStack reviews this content periodically, but you should check current HMRC and GOV.UK guidance before making an important tax, registration, record-keeping or business decision.
Tax treatment depends on individual circumstances. Different rules may apply to trading income, employment income, Capital Gains Tax, National Insurance, VAT and other sources of income.
The SellerStack HMRC Sales & Tax Threshold Checker is a planning tool. It does not determine your legal tax position or replace HMRC guidance or professional advice.
SellerStack is independent and is not affiliated with or endorsed by HM Revenue & Customs.